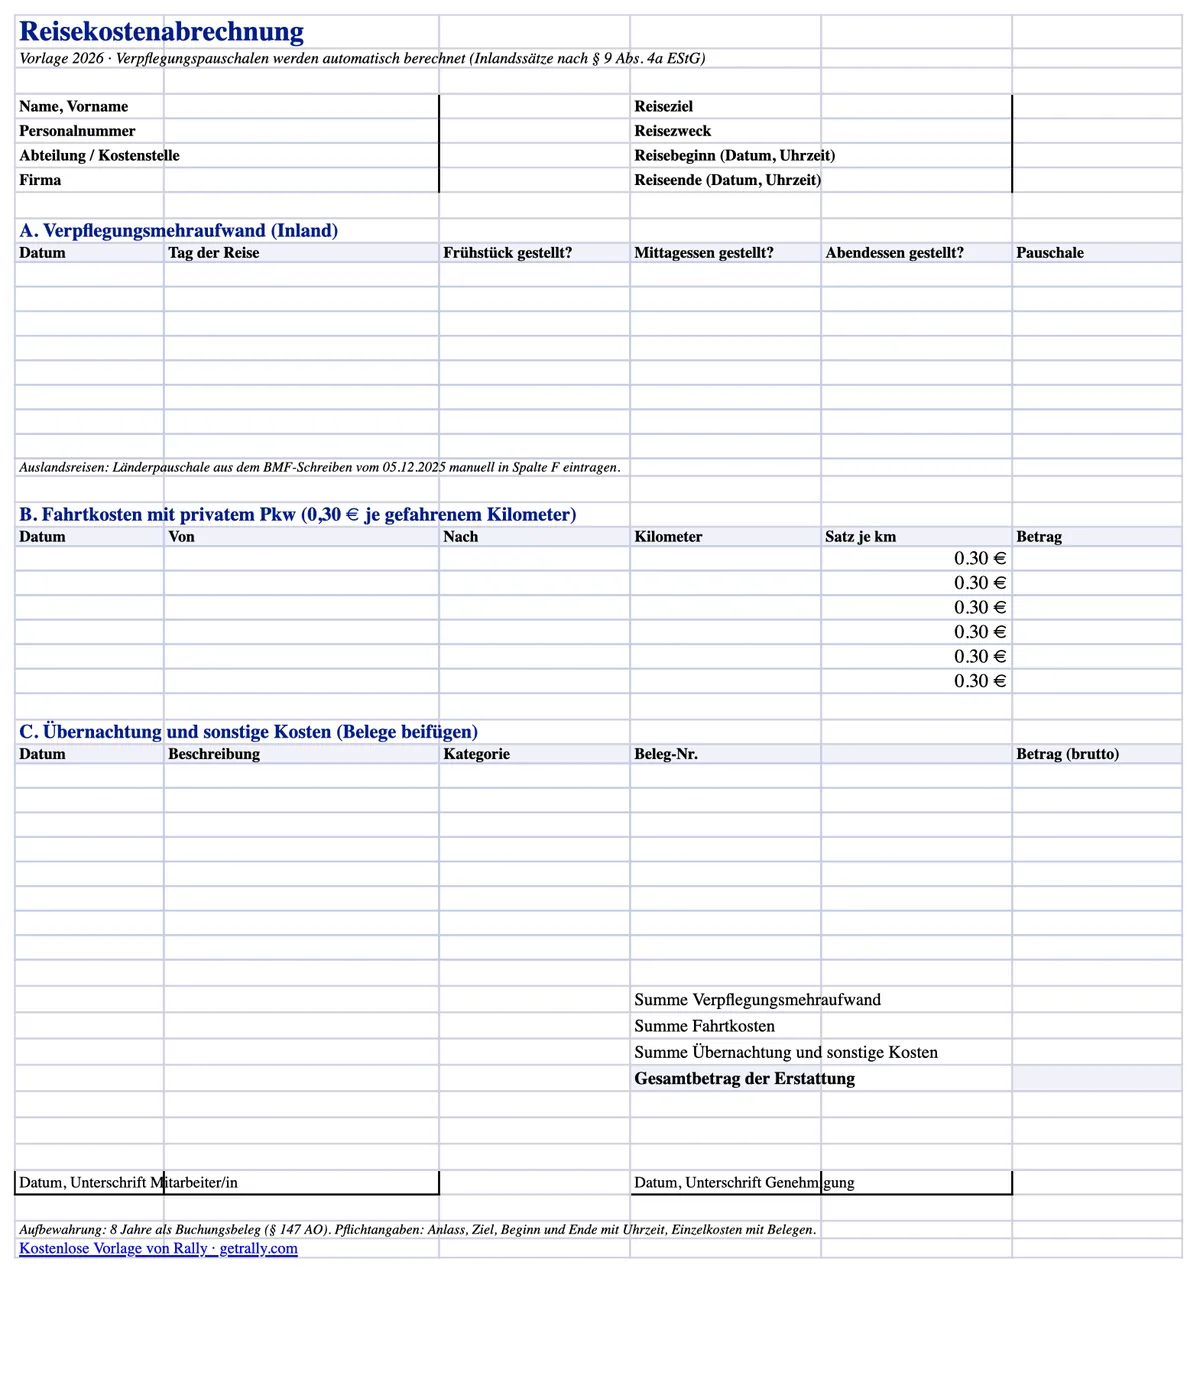
Here is the download up front: our free Reisekostenabrechnung template for 2026 is an Excel form that does the annoying part — the per diem arithmetic — by itself. Pick the day type, tick which meals were provided, and the correct Verpflegungspauschale appears, meal reductions included. Mileage is calculated at €0.30 per kilometre, lodging and incidentals get their own receipted section, and the totals sum to one reimbursement figure.
Download the free Reisekostenabrechnung template (Excel) — no e-mail address required.
The form itself is in German — it is a German tax document — and works in Excel, LibreOffice, and Google Sheets. Below: what the template automates, the mandatory fields the Finanzamt expects, and the 2026 figures behind the formulas. If you only need the rates, see the Verpflegungsmehraufwand 2026 guide: it has the full domestic and foreign tables and a day-by-day calculator.
For a general business form without country-specific rates, use our expense report template, with original-currency and settlement fields.
What the Template Automates
Most free templates are a grid of empty cells. This one encodes the 2026 rules:
- Per diems with automatic meal reductions. For each travel day you select the day type — single-day trip over 8 hours, arrival/departure day, or full 24-hour day — and mark whether breakfast, lunch, or dinner was provided. The sheet applies the €14/€28 domestic rates and subtracts €5.60 per breakfast and €11.20 per lunch or dinner, never going below zero. Those reductions are the single most common per diem error, and they are exactly what a payroll auditor recalculates first.
- Mileage at €0.30/km. Enter the route and kilometres driven; the rate column is pre-filled with the 2026 business-trip rate for private cars and stays editable for motorcycles (€0.20) or a policy rate.
- Lodging and incidentals with receipt references. Hotel, train, parking, tolls, hospitality — each line with a category dropdown and a receipt number, because everything in this section needs a Beleg.
- Header, totals, and signatures. Traveller, cost centre, destination, business purpose, trip start and end with times, three subtotals, one grand total, and signature lines for employee and approver.
For foreign trips, enter the country rate from the BMF table manually in the per diem column — the domestic automation stays out of the way. The full 2026 country table, and every per diem rule in detail, is in our guide to the Verpflegungsmehraufwand 2026.
Worked Example: A Three-Day Domestic Trip
Use this check when reviewing your first completed sheet. An employee travels Monday to Wednesday, receives employer-provided breakfast and lunch on Tuesday, drives 240 km in a private car, and pays a €160 hotel bill personally. Assume the trip meets the business-travel requirements, the three-month limit has not been reached, and the employer reimburses these eligible amounts.
| Claim | Calculation | Reimbursement |
|---|
| Monday, arrival | Arrival-day allowance | €14.00 |
| Tuesday, full day | €28 − €5.60 breakfast − €11.20 lunch | €11.20 |
| Wednesday, departure | Departure-day allowance | €14.00 |
| Private-car mileage | 240 km × €0.30 | €72.00 |
| Hotel paid by employee | Actual cost, with receipt | €160.00 |
| Total | €39.20 + €72 + €160 | €271.20 |
If the company already paid the hotel, the amount still owed to the employee is €111.20, not €271.20. Keep the hotel receipt in the company records, but do not reimburse it twice. If the employee used a company car, do not add the private-car mileage allowance: company-car tax and company-paid fuel are separate from this claim.
Use the Right Tool for Each Cost
| What you need to settle | Next step |
|---|
| Employee-paid business travel | Download the Excel form above and attach the receipts for actual costs. |
| The correct daily meal allowance | Use the German per-diem guide and day calculator before entering the allowance. |
| Tax on private use of a company car | Use the German company-car tax calculator, including annual office days and employee contributions. Its tax estimate is not an expense claim. |
| Fuel or charging paid by the company | Review Rally fuel cards for payment controls and receipt matching; keep these purchases out of the employee reimbursement total. |
The Mandatory Fields (Pflichtangaben)
No statute prescribes a Reisekostenabrechnung form, but the tax rules dictate its content. To keep reimbursements tax-free under § 9 EStG, the record must show:
- Who travelled: name, and in payroll practice the personnel number and cost centre.
- Why: the business purpose (Reisezweck) — "customer visit, project X" beats "meeting".
- Where and exactly when: destination plus start and end of the trip with times. Hours of absence decide between €0, €14, and €28, so times are not optional.
- The itemized costs: per diems (no receipts needed — they are flat rates), transport costs, lodging, and incidentals with receipts attached.
- Provided meals: flagged per day, because they reduce the allowance.
- Signatures or digital approval of traveller and approver, with dates.
An incomplete record does not just annoy the bookkeeper: in a Lohnsteuer-Außenprüfung, reimbursements without proper documentation are reclassified as wages, and the employer owes the payroll tax plus interest — the audit window covers four years.
The 2026 Figures Behind the Formulas
The template hard-codes only figures that are stable for 2026:
| Item | 2026 value |
|---|
| Per diem, absence over 8 hours / arrival & departure days | €14 |
| Per diem, full 24-hour day | €28 |
| Reduction: provided breakfast | €5.60 (20% of €28) |
| Reduction: provided lunch or dinner | €11.20 each (40% of €28) |
| Mileage, private car | €0.30 per km driven |
| Mileage, motorcycle or scooter | €0.20 per km driven |
| Truck-driver overnight flat rate (cab sleeping) | €9 per calendar day |
Two boundaries worth flagging to employees, because 2026 changed one of them:
- €0.30/km is the business-trip rate, unchanged. The commuter allowance (Pendlerpauschale) is a different animal — it rose to €0.38 per distance kilometre from the first kilometre in 2026, but it applies to the home-to-work route in the income tax return, never on an expense report. Mixing the two is a classic error in both directions.
- Per diems stop after three months at the same external location (Dreimonatsfrist), and days below 8 hours of absence pay nothing.
Deadlines, Retention, and Digital Records
Three administrative rules complete the compliance picture:
- Submission deadlines are contractual. Tax law sets no deadline, but employment contracts and CBAs routinely contain Ausschlussfristen of three to six months — after that, the claim can lapse entirely. Encourage monthly submission; receipts do not age well.
- Retention is eight years. Expense reports and their receipts are Buchungsbelege. The Fourth Bureaucracy Relief Act cut their retention from ten to eight years (effective for records whose old period had not expired at the start of 2025). Annual financial statements remain at ten.
- Digital is fine — GoBD applies. Excel and PDF records are accepted if they are complete, unchangeable once filed, and legible for the full period. Scanned receipts can replace paper originals (ersetzendes Scannen) when the process is documented in a Verfahrensdokumentation.
Common Mistakes on German Expense Reports
What auditors and payroll teams actually find:
- Forgotten meal reductions when the hotel rate included breakfast — the reduction applies even if the traveller skipped the buffet.
- Missing times on start and end days, making the per diem tier unverifiable.
- The wrong country rate on border-crossing days: the arrival day uses the country reached before midnight; the return day uses the last place of work abroad.
- Per diems paid past the three-month limit at the same site.
- Pendlerpauschale logic on business trips — one-way distance instead of kilometres driven, or 2026's €0.38 commuter rate instead of €0.30.
- Lost receipts reimbursed without substitute documentation — an Eigenbeleg with date, amount, purpose, and reason for the missing original is the accepted fallback, not a shrug.
When the Spreadsheet Stops Scaling
A good template makes the per diem line painless — that part is genuinely just arithmetic on trip times. What it cannot fix is the paper economy around the trip: drivers fronting fuel and toll costs, receipts photographed weeks later, finance reconciling card statements against forms by hand, and VAT leaking from every non-compliant Beleg.
For fleets and field teams, the higher-leverage move is making the expense report shrink: route fuel, charging, tolls, and on-the-road purchases through company cards with per-employee limits, so employees send each receipt on WhatsApp right after paying and the accounting export is prepared instead of typed. Fuel moves onto fuel cards paid at the pump price, with each station receipt sent through WhatsApp and matched to its payment; the fuel card comparison explains the card types if you are still choosing one. For drivers refuelling within Germany, our guide When is fuel cheapest in Germany? covers the time-of-day and motorway patterns that change the cost per litre. The Reisekostenabrechnung then carries what genuinely belongs on it — per diems and private-car mileage — and nothing else.
Sources
This article is general information, not tax advice. Rates are set by German law and the Federal Ministry of Finance and reviewed annually; verify specifics for your situation with your Steuerberater.